
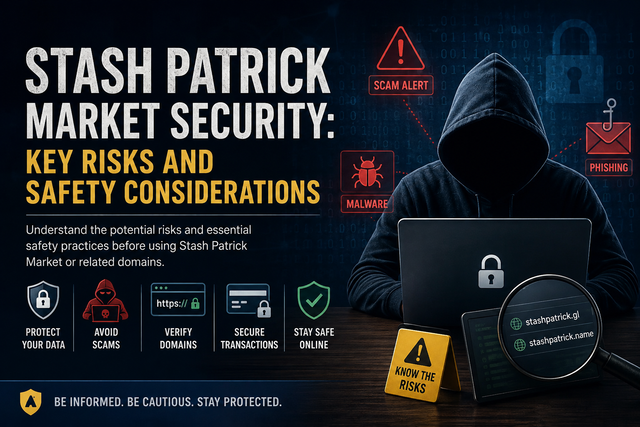
The dark web has become a frequent subject of discussion in cybersecurity, financial crime, and online privacy. While some anonymous networks have legitimate uses, certain hidden services have also been associated with illegal marketplaces, stolen information, fraud, and other forms of cybercrime. Names such as stash patrick Stash Patrick may appear in discussions about these underground environments, particularly in connection with compromised payment information.
Understanding Stash Patrick and similar references is useful when approached from a cybersecurity stashpatrick.cc and risk-awareness perspective. The objective should be to understand how dark web markets create threats, how stolen information can affect consumers and businesses, and how people can protect themselves. Direct participation in illegal marketplaces, purchasing stolen information, or attempting to use compromised financial credentials can create serious security and legal consequences.
What Is the Dark Web?
The internet contains several different layers. The surface web includes websites that search engines can generally index, such as news sites, public business pages, blogs, and online stores.
The deep web consists of resources that are not publicly indexed. Online banking accounts, private email systems, corporate databases, subscription services, and cloud storage are common examples.
The dark web represents a much smaller portion of the internet. It includes services designed to provide additional anonymity and typically requires specialized software or configurations to access.
Dark-web technology is not automatically illegal. Privacy-focused communication can benefit journalists, researchers, whistleblowers, and people living under restrictive conditions. However, anonymity can also be abused by criminals who want to conceal illegal activities.
Understanding the Stash Patrick Reference
Stash Patrick may be mentioned in online discussions concerning underground marketplaces and compromised financial information. Rather than viewing such a name as an ordinary financial service, it is more appropriate to understand it within the wider ecosystem of cybercrime.
Underground marketplaces can connect different participants in criminal activity. One group may obtain information through phishing, malware, or data breaches, while other participants may attempt to distribute or monetize the stolen material.
This division of responsibilities can make cybercrime more organized. However, underground markets are not stable or trustworthy environments. They can be affected by scams, disputes, technical failures, criminal investigations, and law-enforcement operations.
For cybersecurity researchers, the important lesson is how stolen information can move through an ecosystem after an initial compromise.
How Stolen Payment Information Is Obtained
Financial information can be exposed through several attack methods.
Phishing is one of the most common. Attackers may send fraudulent emails, text messages, or websites that imitate banks, retailers, payment providers, or other trusted organizations. Victims may be encouraged to provide passwords, card information, or verification codes.
Data breaches are another major source of exposure. When attackers gain unauthorized access to an organization’s systems, information belonging to customers or employees may be compromised.
Malware can also steal sensitive information from infected devices. Certain malicious programs are designed to collect credentials, browser information, or other valuable data.
Social engineering is particularly dangerous because it targets human behavior. Instead of breaking through a technical security control, criminals may persuade a victim to reveal information or approve a transaction.
Why Dark Web Markets Are Dangerous
Dark-web markets can create risks for both victims and people who attempt to interact with them.
Visitors may encounter malicious advertisements, phishing pages, fraudulent downloads, or malware. Some criminal platforms may themselves be scams designed to steal money or information from users.
The apparent organization of a marketplace can also be misleading. A site may display listings, ratings, customer comments, or other features that resemble legitimate e-commerce platforms. These features do not provide the protections associated with regulated businesses.
There are also legal consequences associated with buying, selling, possessing, or using stolen financial information.
For these reasons, people researching dark-web markets should rely on reputable cybersecurity publications, academic research, government reports, and law-enforcement announcements rather than attempting to participate in underground transactions.
Risks to Consumers
Consumers can experience significant problems when their payment information is compromised.
Unauthorized purchases may be the first visible sign of fraud. However, stolen payment information can sometimes be combined with other personal details, increasing the risk of identity-related crime or account takeover.
Password reuse can make these incidents more serious. If the same password is used across several websites, a compromise at one service may provide attackers with opportunities to target other accounts.
Consumers should therefore use unique passwords for financial and other important accounts. A reputable password manager can make managing different credentials easier.
Multi-factor authentication should also be enabled wherever possible.
Monitoring Financial Accounts
Regular financial monitoring can help consumers detect suspicious activity quickly.
Many banks and card providers offer transaction alerts through mobile applications, email, or text messages. These notifications can provide immediate awareness when purchases occur.
Consumers should review account statements and report unfamiliar transactions to their financial institution promptly.
It is also important to keep contact information up to date with financial providers so that security notifications can reach the correct person.
Early detection cannot prevent every incident, but it can limit the potential consequences of unauthorized activity.
The Role of Businesses
Businesses are major targets because they may process or store large quantities of payment information.
Organizations should follow a layered approach to security. Access to sensitive information should be restricted according to job responsibilities, while authentication controls should protect important systems.
Encryption can help protect information during storage and transmission. Tokenization can reduce the exposure of actual payment-card credentials by replacing sensitive values with substitute tokens during certain transactions.
Regular vulnerability assessments and software updates are also essential. Security teams should monitor systems for unusual behavior and maintain procedures for responding to incidents.
Employee education is equally important because phishing and social engineering frequently target staff members.
Payment Tokenization and Modern Security
Tokenization has become an important tool in modern payment security.
Instead of repeatedly transmitting an actual card number, payment systems can use a token that represents the underlying credential. Depending on the system, a compromised token may have limited usefulness outside its intended environment.
This approach reduces the number of locations where actual payment credentials need to be exposed.
Tokenization works best as part of a broader security strategy that includes encryption, strong authentication, monitoring, access controls, and fraud detection.
How Financial Institutions Detect Fraud
Banks and payment processors use sophisticated systems to identify suspicious transactions.
These systems can analyze factors such as transaction location, timing, purchase amounts, merchant information, and historical customer behavior.
If a transaction differs significantly from normal activity, a financial institution may request additional verification or temporarily restrict the transaction.
Machine-learning and behavioral-analysis technologies can help identify complex patterns that traditional rules may overlook.
Despite these technologies, no system can eliminate financial fraud completely. Consumers still play an important role by protecting their credentials and reporting suspicious activity quickly.
Responsible Cybersecurity Research
Researchers may study dark-web markets to understand emerging cybercrime trends. Such research can provide valuable information about how criminals obtain data, organize operations, and attempt to monetize stolen information.
However, responsible research does not require purchasing stolen credentials or participating in illegal transactions.
Researchers can use public threat-intelligence reports, academic studies, court records, government announcements, and security-company research.
This approach can provide meaningful insight while reducing exposure to malware, scams, sensitive information, and legal risks.
Why Dark Web Markets Keep Evolving
Underground marketplaces are rarely permanent. A marketplace may disappear because of technical problems, internal disputes, scams, arrests, or law-enforcement intervention.
Criminal participants may then attempt to migrate to other platforms or communication channels.
This demonstrates why cybersecurity defenses cannot focus exclusively on individual websites or marketplace names. The underlying threat comes from the broader ecosystem of data theft, fraud, and financial exploitation.
Reducing the availability and usefulness of stolen information is therefore an important defensive objective.
Protecting Yourself From Emerging Threats
Individuals can take several practical steps to improve their digital security.
Use unique, strong passwords for important accounts and enable multi-factor authentication whenever available. Keep operating systems, browsers, and applications updated. Avoid unexpected links and attachments, particularly when they request financial information.
Never provide authentication codes to someone who contacts you unexpectedly. Legitimate financial institutions generally have established procedures for verification and will not require customers to disclose sensitive credentials through suspicious channels.
Consumers should also be cautious about websites promising unusually easy access to financial products or other people’s accounts.
Conclusion
Understanding Stash Patrick and the risks associated with dark-web markets is ultimately a cybersecurity awareness exercise. References to underground marketplaces can illustrate how stolen financial information becomes part of a wider criminal ecosystem involving data breaches, phishing, malware, social engineering, and fraud.
The safest response is not to participate in these environments but to understand the risks they represent. Consumers can strengthen their security through unique passwords, multi-factor authentication, transaction monitoring, and careful handling of suspicious communications.
Businesses can reduce exposure through encryption, tokenization, access controls, vulnerability management, employee training, and effective incident-response procedures.
The dark web will continue to evolve alongside legitimate privacy technologies and criminal activity. By focusing on education, prevention, and responsible research, individuals and organizations can better understand emerging threats while avoiding the substantial risks associated with illicit marketplaces.
